 Dost Pakistan Journeys Tours and safaris in the North & South Pakistsn
“`html
Pakistan’s Tax Justice Under Scrutiny: The Withholding Tax Dilemma for Transporters
The News: A Legal Challenge to Tax Disparity
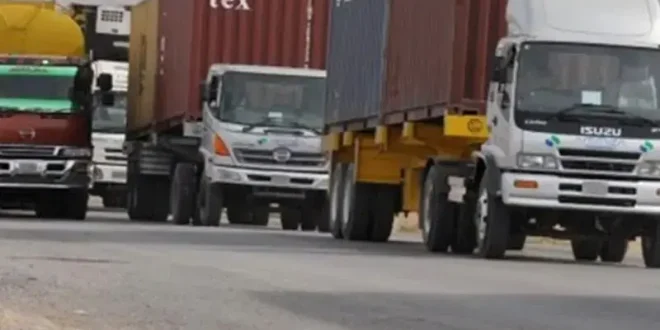
The Islamabad High Court (IHC) has recently taken up a significant petition challenging the federal government’s decision to increase the withholding tax (WHT) on general goods transportation from 6% to 7%, a measure introduced through the Finance Act, 2026. This legal action, spearheaded by I.S. Enterprises and Shaheen Freight Services, contends that the enhanced tax rate is fundamentally discriminatory, especially when contrasted with the much lower 2% WHT applicable to oil tanker contractors. The petitioners argue that imposing different tax rates based solely on the nature of goods transported, despite using identical vehicles and infrastructure, violates constitutional principles of equality before the law and protection of law, enshrined in Articles 4 and 25 of the Constitution of Pakistan. The IHC has issued notices to key government bodies, including the Federal Board of Revenue (FBR) and the Attorney General for Pakistan (AGP), signalling the gravity of the constitutional challenge, with the next hearing slated for September 17.
Background: Understanding Pakistan’s Withholding Tax Regime
Withholding tax (WHT), often referred to as tax deducted at source, is a common mechanism employed globally by governments, including Pakistan’s FBR, to collect revenue efficiently. It acts as an advance payment of income tax, collected by a payer (e.g., a company hiring transport services) on behalf of the recipient (the transporter) and remitted directly to the tax authority. This system broadens the tax net, ensures a steady flow of government revenue, and simplifies tax administration, particularly for sectors with fragmented operations like transportation, where tracking individual income might be challenging.
The Finance Act, typically an annual legislative instrument, outlines the government’s fiscal policy for the upcoming year, including tax adjustments aimed at achieving revenue targets or stimulating specific economic activities. The 2026 Act, in this instance, increased WHT rates across various services, including courier, logistics, hotels, and general transport. However, the contentious point lies in the historical concession granted to oil tanker operators under the Second Schedule of the Income Tax Ordinance, 2001. This preferential treatment, according to the petitioners, has long been justified by the government on the grounds that strikes by oil tankers could cripple fuel supplies nationwide, thereby posing a threat to national security and economic stability. While this rationale addresses a critical vulnerability, it now faces direct scrutiny regarding its fairness when other essential transport services bear a significantly higher tax burden.
The constitutional challenge invoking Articles 4 and 25 is pivotal. Article 4 guarantees that every citizen has the inalienable right to be treated in accordance with the law and to enjoy its protection. More specifically, Article 25 asserts that “all citizens are equal before law and are entitled to equal protection of law.” While this does not preclude all classifications, it mandates that any distinction made by law must be based on an “intelligible differentia” (a reasonable basis for distinction) and bear a “rational nexus” (a logical connection) to the objective the law seeks to achieve. The petitioners argue that differentiating tax rates for the same vehicle and service based purely on the type of cargo fails this stringent constitutional test, particularly when no economic impact assessment supports the hike.
Impact on Pakistan: Economic Repercussions and Business Environment
The transport sector is the lifeblood of Pakistan’s economy, facilitating trade, commerce, and the movement of goods from producers to consumers. Any increase in its operational costs, such as higher withholding taxes, inevitably translates into elevated prices for goods across the supply chain. This pass-through effect often contributes to inflationary pressures, ultimately burdening the end consumer. In a country already grappling with economic challenges and cost-of-living concerns, such tax hikes can exacerbate financial strain on households and businesses alike.
Beyond inflation, the perceived discriminatory taxation can have broader implications for Pakistan’s business climate. An inequitable tax regime can foster resentment, discourage formal sector participation, and potentially lead to tax avoidance, undermining the FBR’s efforts to broaden the tax base. Businesses thrive on predictability, fairness, and a level playing field. When one segment of an industry is granted significant concessions while another, performing an arguably identical service, is taxed higher, it creates market distortion and can stifle competition. For general goods transporters, who serve a vast array of industries and consumers, a higher tax burden without apparent economic justification feels unjust and could impact their profitability and capacity for investment in fleet modernization or expansion.
Furthermore, the petitioners’ assertion that no publicly available economic impact assessment or empirical study was conducted to justify the 7% WHT increase raises questions about the transparency and evidence-based nature of tax policy formulation in Pakistan. Sound fiscal policy requires rigorous analysis of potential consequences to avoid unintended negative outcomes and ensure sustainable economic growth.
Analysis: Balancing Revenue, Equity, and Economic Realities
The IHC’s decision to take up this petition underscores a critical examination of tax policy through the lens of constitutional law. From the petitioners’ perspective, their argument is robust: if the infrastructure, vehicles, and fundamental service (transportation) are the same, the distinction based on cargo type appears arbitrary and lacking a rational basis under Article 25. The historical justification for oil tanker concessions, while acknowledging their strategic importance, doesn’t automatically negate the constitutional demand for equality for other essential transport services. General goods transporters play an equally vital role in ensuring the flow of essentials and industrial raw materials, making their services indispensable.
The government’s likely defence will pivot on the imperative for revenue generation and the strategic significance of the oil and gas supply chain, arguing that the unique vulnerabilities associated with fuel distribution warrant a distinct classification. However, courts generally require more than mere administrative convenience or revenue needs to uphold a classification against an equality challenge; there must be a genuine, discernible difference that justifies the differential treatment. The argument that general goods transporters, despite providing equally vital services, do not resort to strikes as frequently as oil tanker operators, highlights a complex interplay of economic leverage and policy considerations, but it may not hold sufficient legal weight to overcome a constitutional challenge on equality grounds.
This case has the potential to set a significant precedent for tax policy in Pakistan. Should the IHC rule in favour of the petitioners, it could force the FBR and the government to re-evaluate their tax classification criteria, particularly concerning similar services with disparate tax rates. It could compel greater transparency in policy-making, demanding robust economic impact assessments before imposing new tax burdens. Conversely, if the court upholds the current WHT regime, it would solidify the government’s discretion in classifying taxpayers based on broader economic or strategic considerations, even if they appear to lead to unequal treatment for similar services, potentially strengthening the state’s hand in future tax legislation.
Ultimately, this legal battle highlights the perpetual tension between a government’s imperative to raise revenue for national development and its constitutional obligation to ensure fairness and equality before the law. For Pakistan, a developing economy striving for stability and growth, striking the right balance in its tax regime is not just a matter of legal compliance but a foundational element for fostering a predictable, equitable, and vibrant business environment.
“`
