 Dost Pakistan Journeys Tours and safaris in the North & South Pakistsn
Related Articles
Pakistan’s Banks Entrenched in Government Debt: A Deep Dive into Fiscal Dependence
SEO Title: Pakistan Banking Sector: Why Government Borrowing Dominates Private Lending & Hinders Growth
The News: A Persistent Trend of Government Reliance
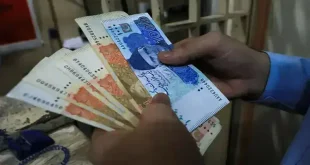
Recent financial industry insights from Karachi indicate a deepening reliance of Pakistan’s banking sector on government borrowing for profitability, a trend projected to continue through the current fiscal year (FY27). Despite repeated calls from the State Bank of Pakistan (SBP) and the government to boost lending to the private sector, particularly small and medium enterprises (SMEs), opportunities for private sector credit remain severely limited.
- Government Borrowing Surge: Federal government borrowing from commercial banks escalated to Rs5.9 trillion in FY26, a significant jump from Rs5.4 trillion in FY25.
- Private Sector Squeeze: In stark contrast, the private sector received a mere Rs1.4 trillion in credit during FY26.
- Declining Private Sector Engagement: The advance-to-deposit ratio (ADR), a key indicator of banks’ lending to the private sector, plummeted to a low of 35.2% in June 2026 from 38.1% in June 2025, reportedly one of the lowest in the region.
- Preference for Government Securities: The investment-to-deposit ratio (IDR) stood at 104.2% in June 2026, highlighting banks’ preference to park almost all their funds in government papers due to their perceived safety and attractive yields.
- Bleak Outlook: Bankers foresee no significant change in FY27, citing a lack of expected recovery in the manufacturing sector and minimal growth in exports, coupled with ongoing geopolitical uncertainties.
Background: The Anatomy of Fiscal Dependence
To fully grasp the implications of this trend, it’s crucial to understand the underlying economic mechanisms at play in Pakistan. The government’s pervasive presence in the credit market is not an isolated event but a symptom of deeper structural issues, primarily the persistent fiscal deficit.
Understanding Key Ratios:
- Advance-to-Deposit Ratio (ADR): This ratio measures the proportion of a bank’s deposits that are extended as loans to its customers. A high ADR suggests aggressive lending and strong private sector demand, while a low ADR, as seen in Pakistan, indicates either a lack of viable lending opportunities or banks’ reluctance to lend due to perceived risk. It directly reflects the health and activity of the private sector.
- Investment-to-Deposit Ratio (IDR): Conversely, the IDR indicates how much of a bank’s deposits are invested in instruments other than direct loans, predominantly government securities like Treasury Bills (T-bills) and Pakistan Investment Bonds (PIBs). A high IDR signifies banks’ preference for low-risk, sovereign-guaranteed investments, often at the expense of private sector credit.
The Fiscal Dilemma:
Pakistan has long grappled with a significant fiscal deficit, where government expenditure consistently outstrips its revenue. This gap necessitates continuous borrowing, and a primary source for this financing is the domestic banking sector. Banks, particularly in an environment of high-interest rates (often employed by the SBP to manage inflation and stabilize the currency), find government securities extremely attractive. These instruments offer guaranteed returns with virtually zero default risk, making them a “safe haven” for capital compared to potentially riskier private sector ventures.
The consequence is that a substantial portion of the national budget is consumed by interest payments on this accumulated debt. As reported, nearly 50% of the federal government’s revenue in FY26 was allocated to interest servicing, severely limiting the fiscal space for crucial public spending on development projects, education, healthcare, and poverty alleviation.
Moreover, the general economic environment in Pakistan, characterized by below 4% growth and policymakers’ primary focus on external financial stability, has done little to inspire confidence or create sufficient investment opportunities for the private sector. This creates a challenging ecosystem where businesses, especially SMEs, struggle to secure credit even when they have growth potential.
Impact on Pakistan: The Crowding-Out Effect and Stifled Growth
The banking sector’s over-reliance on government borrowing has profound and multi-faceted impacts on the broader Pakistani economy, perpetuating a cycle of underdevelopment and hindering sustainable growth.
1. The Crowding-Out Effect:
This is perhaps the most critical consequence. When the government becomes the dominant borrower in the market, it absorbs a disproportionately large share of available credit. This “crowds out” the private sector, making it difficult and more expensive for businesses to access the capital they need for expansion, innovation, and job creation. Small and medium-sized enterprises (SMEs), often the backbone of an economy, are particularly vulnerable as they typically lack the collateral or established credit history to compete with sovereign borrowing.
2. Stagnation of Private Sector Investment:
A restricted credit supply, coupled with higher borrowing costs (as banks may demand higher returns due to limited private sector options or simply prefer risk-free government bonds), discourages private investment. This is evident in the low domestic investment figures cited by experts, indicating that businesses are either unwilling or unable to take on high-cost debt in an uncertain economic climate. A stagnant private sector directly translates to fewer new businesses, limited industrial growth, and a lack of job opportunities.
3. Hindered Economic Growth and Productivity:
Sustainable economic growth is driven by productive investment, technological advancement, and increased productivity, largely spearheaded by the private sector. When capital is diverted from these productive avenues into financing government consumption or debt servicing, the economy’s long-term growth potential is severely curtailed. This contributes to Pakistan’s struggle to achieve its growth targets and improve living standards.
4. Exacerbated Fiscal Burden:
The continuous cycle of borrowing leads to an ever-increasing national debt and, consequently, higher interest payments. As half of the government’s revenue already goes towards debt servicing, this leaves little room for essential public services and development projects. It creates a precarious situation where the government’s ability to respond to future economic shocks or invest in human capital is severely constrained.
5. Risk to Financial Stability (Long-Term):
While government securities are considered safe in the short term, an excessive concentration of banks’ portfolios in sovereign debt can pose systemic risks in the long run. Any significant deterioration in the government’s fiscal health or creditworthiness could have ripple effects across the entire financial system. Furthermore, it distorts the banking sector’s fundamental role of intermediating capital for productive economic activities.
Analysis: The Vicious Cycle and Policy Imperatives
The current scenario in Pakistan’s banking sector is a complex interplay of fiscal pressures, economic uncertainties, and risk aversion, creating a vicious cycle that demands a multi-pronged policy response. Banks are rational actors, and their preference for government securities is a direct reflection of market realities.
The Banks’ Perspective:
From a bank’s viewpoint, the decision is straightforward:
- Risk-Adjusted Returns: Government bonds offer attractive, virtually risk-free returns, especially in high-interest rate environments. Lending to the private sector, conversely, involves credit risk, higher operational costs for due diligence, and potential non-performing loans (NPLs).
- Lack of Viable Demand: As experts like S.S. Iqbal suggest, if domestic investment is among the lowest in the region, it indicates a fundamental lack of creditworthy private sector projects or a significant downturn in business confidence. High-cost money (loans) becomes even less appealing for businesses facing geopolitical uncertainties and a weak economic outlook.
- Regulatory Environment: While the SBP urges private sector lending, regulatory frameworks often incentivize holding safer assets, especially during periods of economic instability.
The Policy Conundrum:
Policymakers face a significant challenge. The focus on “external fronts,” while necessary for macroeconomic stability and international financing, often leaves the domestic fiscal deficit unaddressed, forcing the government to rely heavily on bank borrowing. This short-term solution exacerbates long-term structural problems.
The declining advance-to-deposit ratio is a stark indicator of weak private sector growth, not just a banking issue. It reflects a broader economic malaise: low investment, struggling manufacturing and export sectors, and an overall environment not conducive to risk-taking. The call for banks to boost SME lending, while well-intentioned, often falls flat if the underlying economic conditions and demand for credit from a healthy, growing private sector are not present.
Breaking the Cycle:
Breaking this cycle requires a concerted and sustained effort on multiple fronts:
- Fiscal Consolidation: The most crucial step is to reduce the government’s borrowing needs through prudent fiscal management. This involves expanding the tax base, controlling non-development expenditure, and prioritizing spending. A credible fiscal roadmap can signal commitment and reduce pressure on domestic banks.
- Enhancing Private Sector Confidence: Policies must be geared towards creating a stable, predictable, and attractive environment for private investment. This includes policy consistency, improving the ease of doing business, resolving long-standing issues in the manufacturing sector, and supporting export-oriented industries.
- Targeted Credit Mechanisms: Beyond general directives, specific mechanisms or guarantee schemes could de-risk private sector lending for banks, especially to SMEs and productive sectors. The SBP could explore innovative financing tools to channel credit where it’s most needed.
- Addressing Structural Economic Issues: Long-term solutions lie in fundamental reforms that boost productivity, diversify the economy, and improve human capital. This will naturally generate more viable private sector projects and increase demand for credit.
- Promoting Domestic Savings and Investment: Strategies to boost domestic savings can provide a more sustainable funding source for both government and private sector, reducing reliance on bank credit and external borrowing.
The outlook for FY27 suggests a continuation of the status quo unless fundamental shifts in fiscal and economic policy are implemented. The persistent dependence of Pakistan’s banking sector on government borrowing underscores a critical structural challenge that, if left unaddressed, will continue to impede the nation’s journey towards sustainable economic growth and prosperity.
“`