 Dost Pakistan Journeys Tours and safaris in the North & South Pakistsn
Related Articles
“`html
LHC Ruling: Insurance Policyholder Complaints Beyond Consumer Court Jurisdiction in Pakistan
A landmark decision by the Lahore High Court redefines the legal landscape for insurance dispute resolution, directing policyholders to specialized tribunals instead of consumer courts.
The News: A Jurisdictional Shift for Insurance Claims
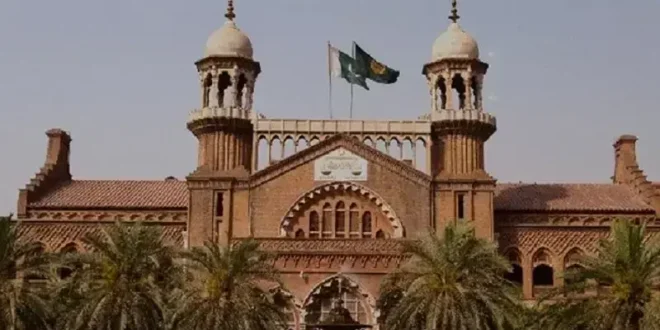
In a significant development for Pakistan’s legal and insurance sectors, the Lahore High Court (LHC) has ruled that consumer courts do not possess the authority to adjudicate complaints lodged by policyholders against insurance companies. This pivotal decision, issued by Justice Jawad Hassan, stems from a petition filed by the United Insurance Company of Pakistan Limited challenging an order from the District Consumer Court in Bhakkar.
The consumer court had previously deemed a policyholder’s complaint maintainable, arguing that the dispute arose from the provision of insurance services. However, the LHC set aside this ruling, emphasizing that the lower forum failed to adequately consider the specific statutory framework governing insurance, particularly Section 122 of the Insurance Ordinance, 2000. Justice Hassan highlighted that Section 122(3) of this federal ordinance explicitly designates specialized tribunals as the exclusive forum for claims made by policyholders against insurers, effectively barring other courts from exercising jurisdiction over such matters. The case has now been remanded back to the consumer court, with a directive to issue a fresh, reasoned decision on maintainability within one month, strictly adhering to the law and established judicial precedents.
Background: Understanding the Legal Framework
To fully grasp the implications of the LHC’s decision, it’s crucial to understand the interplay between general consumer protection laws and specialized federal legislation. Consumer courts were established with the primary aim of providing accessible, expeditious, and cost-effective justice to consumers facing issues with goods or services. They operate under provincial consumer protection acts, designed to safeguard general consumer rights.
However, the insurance sector in Pakistan is governed by a comprehensive federal law: the Insurance Ordinance, 2000. This ordinance is a specialized piece of legislation that meticulously outlines the regulatory framework for insurance companies, their operations, and importantly, the mechanisms for dispute resolution. Section 122 of this Ordinance is particularly significant, as it establishes specific tribunals for handling grievances arising from insurance policies. The LHC’s ruling underscores the legal principle of “lex specialis derogat legi generali” – a special law overrides a general law. In this context, the federal Insurance Ordinance, being a special law for the insurance sector, takes precedence over the general provincial consumer protection acts.
Furthermore, the judgment is rooted in constitutional principles, specifically Article 143 of the Constitution of Pakistan, which dictates that where a provincial law conflicts with a federal law on a subject in the concurrent legislative list, the federal law shall prevail. The LHC also referenced established judicial precedents, including the landmark Adamjee Insurance Company case, which has consistently upheld the supremacy of specialized legislation in such jurisdictional conflicts.
Impact on Pakistan: Implications for Policyholders, Insurers, and the Legal System
For Policyholders:
- Change in Forum: Policyholders will no longer be able to approach consumer courts for disputes related to their insurance policies. Instead, they must now seek redress through the specialized tribunals established under the Insurance Ordinance, 2000.
- Access to Justice Concerns: While specialized tribunals offer expertise, their accessibility, geographical reach, and procedural swiftness compared to consumer courts could become a concern for ordinary citizens, particularly in remote areas.
- Awareness Gap: There is a critical need for increased awareness among the general public regarding the correct forum for lodging insurance-related complaints.
For Insurance Companies:
- Jurisdictional Clarity: The ruling provides much-needed clarity for insurance companies, streamlining the dispute resolution process by confining it to a single, specialized forum.
- Reduced Forum Shopping: Insurers will be protected from facing similar complaints across multiple general forums, potentially leading to more consistent and predictable outcomes.
- Expertise in Adjudication: Disputes will now be heard by tribunals potentially possessing a deeper understanding of complex insurance contracts, actuarial principles, and industry specifics.
For the Legal System and Regulator:
- Reinforcing Legal Principles: The decision reinforces fundamental constitutional and legal principles concerning the hierarchy of laws and the role of specialized tribunals.
- Role of SECP: The Securities and Exchange Commission of Pakistan (SECP), as the primary regulator of the insurance sector, will have an even more crucial role in ensuring the efficiency, accessibility, and effectiveness of these specialized tribunals.
- Precedent for Other Sectors: This ruling could set a precedent for similar jurisdictional challenges in other regulated sectors that also have their own specialized laws and dispute resolution mechanisms.
Analysis: Balancing Specialization with Consumer Access
The Lahore High Court’s ruling, while legally sound and based on established constitutional and statutory principles, presents a dual perspective. On one hand, it brings much-needed legal clarity and consistency to the resolution of insurance disputes. Specialized tribunals are inherently better equipped to handle the intricacies of insurance contracts, underwriting, and claims processing, ensuring that decisions are based on expert understanding rather than general consumer law interpretations. This alignment with the specific provisions of the Insurance Ordinance, 2000, is a positive step towards uniform application of the law across the insurance industry.
On the other hand, the primary challenge emerging from this decision lies in its potential impact on consumer access to justice. Consumer courts were designed to be user-friendly, less formal, and often quicker forums for grievances. Shifting these complaints to specialized tribunals, whose structure, procedural rules, and accessibility might be less familiar or more cumbersome for the average policyholder, could inadvertently create barriers. The effectiveness of this jurisdictional shift will heavily depend on how robust, efficient, and consumer-friendly the specialized tribunals under the Insurance Ordinance, 2000, prove to be.
The way forward demands a concerted effort. The SECP, in collaboration with the government, must prioritize strengthening these specialized tribunals. This includes ensuring they are adequately resourced, geographically accessible, and capable of delivering timely and fair judgments. Simultaneously, an aggressive public awareness campaign is vital to educate policyholders about the correct legal avenues for their insurance-related grievances. While the LHC’s decision upholds the letter of the law, the spirit of consumer protection requires that the specialized forums are not just legally correct, but also practically effective and accessible for all citizens seeking justice regarding their insurance policies.
“`