 Dost Pakistan Journeys Tours and safaris in the North & South Pakistsn
Related Articles
“`html
Pakistan’s Pasban Scheme: A Strategic Play to Boost Formal Remittances and Forex Reserves
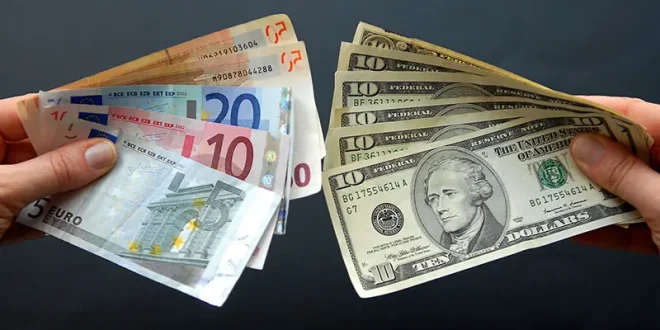
Pakistan has unveiled its latest strategy to bolster its foreign exchange reserves and encourage the use of official banking channels for money transfers from overseas Pakistanis. The new Pasban Remittance Reward Scheme, a substantial Rs16 billion annual initiative funded entirely by the country’s banking industry, marks a significant shift in how the nation aims to attract crucial remittances.
The News: A New Era of Remittance Incentives
The State Bank of Pakistan (SBP), in collaboration with the Pakistan Banks Association (PBA), has launched the Pasban Remittance Reward Scheme. This initiative is set to distribute Rs16 billion in annual cash prizes to beneficiaries of home remittances, with no direct cost to the national exchequer. This substantial sum will be awarded through quarterly draws, totaling over 10,000 winners annually.
- Prize Structure: Each quarterly draw boasts a top prize of Rs100 million, alongside 20 prizes of Rs25 million, 100 prizes of Rs10 million, and 2,400 prizes of Rs1 million.
- Eligibility: Beneficiaries automatically qualify by receiving at least $100 (or equivalent) into an eligible bank account or digital wallet in each of the three months within a quarter. The number of entries increases with the value of the remittance, incentivizing larger transfers.
- Exclusions: Critically, cash-over-counter remittances and funds credited to Roshan Digital Accounts (RDAs) or foreign-currency accounts are excluded, emphasizing a focus on direct local currency deposits through formal banking.
- Timeline: The first qualifying period runs from October 1 to December 31, 2026, with the inaugural draw scheduled for January 15, 2027.
- Funding & Oversight: The scheme is bank-funded, developed under SBP patronage, and will be administered with robust, independently audited systems to ensure transparency and fairness in the draw process.
SBP Governor Jameel Ahmad highlighted that this scheme is a continuation of efforts to maintain the attractiveness of formal remittance channels, acknowledging the vital contribution of overseas Pakistanis to the nation’s economic stability.
Background: Pakistan’s Lifeline – Remittances and Forex Challenges
Pakistan has historically grappled with current account deficits and the perennial need to bolster its foreign exchange reserves. Workers’ remittances serve as a crucial lifeline, acting as the largest source of external financing and a vital support system for millions of families across the country. These inflows not only help meet household expenses but also contribute significantly to education, healthcare, and investment within the economy.
For years, informal channels for money transfers, often referred to as ‘hundi’ or ‘hawala,’ have diverted a considerable portion of remittances away from the official banking system. This informal economy bypasses regulatory oversight, deprives the nation of valuable foreign exchange that could shore up official reserves, and contributes to a shadow economy. The SBP and successive governments have consistently sought to channel these funds through formal routes to strengthen the national currency, manage the external account, and enhance financial transparency.
In his address, the SBP Governor noted the substantial improvement in Pakistan’s external account, with foreign exchange reserves soaring from below $3 billion in February 2023 to $21.4 billion. He emphasized that this growth was primarily driven by market purchases rather than external debt accumulation. Workers’ remittances have also seen remarkable growth, nearly doubling from $21.7 billion in FY19 to a record $41.6 billion in FY26, underscoring their increasing importance.
Previous incentive schemes, such as the Sohni Dharti Remittance Programme, aimed to achieve similar objectives. However, as these programs expanded, their costs to the national exchequer grew. The Pasban scheme represents a strategic evolution towards a more sustainable, market-oriented model, with the banking industry now taking the lead in funding these vital incentives. This transition signifies a collective effort to manage the national economy more effectively.
Impact on Pakistan: Boosting Stability and Financial Inclusion
The Pasban Remittance Reward Scheme has the potential to generate several significant positive impacts for Pakistan’s economy and its citizens:
- Strengthening Foreign Exchange Reserves: By actively incentivizing formal channels, the scheme aims to funnel a greater proportion of remittances into the official banking system. This directly translates to increased foreign exchange inflows, bolstering the SBP’s reserves and improving the nation’s balance of payments.
- Enhanced Economic Stability: Higher official remittance inflows contribute to managing the current account deficit, stabilizing the rupee, and enhancing investor confidence. This creates a more predictable economic environment conducive to growth and investment.
- Financial Inclusion: The scheme encourages beneficiaries to receive funds directly into bank accounts or digital wallets. This push away from cash-over-counter transactions can promote greater financial literacy and inclusion, integrating more individuals into the formal banking ecosystem.
- Empowerment of Beneficiaries: Direct cash prizes for recipients can provide substantial financial upliftment for winning families, potentially contributing to savings, investments, or meeting essential household needs.
- Cost-Effective Government Strategy: By being entirely funded by the banking industry, the scheme alleviates the financial burden on the national exchequer, making it a sustainable and attractive model for the government. The PBA’s commitment, reportedly close to Rs100 billion annually towards remittance-related support, demonstrates the industry’s significant buy-in.
- Transparency and Data: Greater reliance on formal channels improves data collection on remittance flows, providing policymakers with a clearer picture of economic activity and enabling more informed decision-making.
While the benefits are clear, the scheme will face the ongoing challenge of effectively competing with the speed, convenience, and sometimes lower perceived costs of informal channels. Its success will depend on its ability to consistently draw a substantial portion of remittances away from these alternatives.
Analysis: A Smart, Sustainable Evolution in Policy
The Pasban Remittance Reward Scheme represents a well-thought-out, evolved approach to a persistent economic challenge. Its design reflects several strategic considerations:
- Shift to Industry Funding: The move from government-funded schemes (like Sohni Dharti) to bank-funded incentives is a crucial strategic pivot. It makes the program fiscally sustainable for the government and aligns the interests of the banking sector directly with increasing formal inflows. Banks benefit from increased deposits and transaction volumes, justifying their significant investment.
- Targeting the Recipient: By rewarding the beneficiary in Pakistan, the scheme directly incentivizes the end-user to demand formal transfers. This is a pragmatic approach, as beneficiaries often have a strong influence on how funds are received, especially when substantial rewards are on offer. The automatic, free participation removes barriers, making it highly accessible.
- Lottery-Based Incentive Model: The lottery model, with its life-changing top prizes, aims to create a significant buzz and aspiration. While the odds of winning a top prize are low for any single individual, the sheer magnitude of the potential reward can be a powerful motivator, drawing attention and participation in a way smaller, guaranteed incentives might not. The tiered prize structure, however, also ensures a broader distribution of smaller prizes, maintaining engagement across various remittance levels.
- Strategic Exclusions: Excluding cash-over-counter transactions reinforces the objective of promoting bank account usage and financial digitization. The exclusion of Roshan Digital Account (RDA) inflows suggests that RDAs, a separate and successful initiative for overseas Pakistanis, likely have their own distinct incentive structures or are viewed as a different segment of foreign currency deposits.
- Scalability and Transparency: The Rs16 billion annual commitment is substantial, demonstrating serious intent. The use of 1LINK’s algorithm-based system and independent audits for draws ensures integrity, which is paramount for public trust in such a scheme.
- Broader Economic Strategy: Pasban is not an isolated initiative; it’s part of a broader, concerted effort by the SBP and the government to stabilize the economy, build foreign exchange buffers, and foster trust in the formal financial system. In a country constantly managing external account pressures, every mechanism to boost official inflows is critical.
While the scheme is innovative and robust, its ultimate success will hinge on continuous awareness campaigns, ease of use for both senders and receivers, and the ability of the banking system to handle increased volumes efficiently. The “Pasban Remittance Reward Scheme” represents a proactive and sustainable step in Pakistan’s ongoing journey towards economic resilience, leveraging the power of financial incentives to channel a vital national resource through legitimate and beneficial channels.
“`